A car insurance deductible is the out-of-pocket amount a driver pays before the policy covers a claim. A car insurance deductible applies to collision, comprehensive, uninsured motorist property damage, and personal injury protection coverage. Standard deductible options range from $250 to $2,000 per claim. Each claim resets the deductible, and no annual cap applies. Motor vehicle insurance prices rose 2.8% in 2025, according to the Bureau of Labor Statistics. Drivers need premium quotes at two or three deductible levels to compare annual savings against claim costs. Insurance Navy helps drivers compare car insurance quotes across the United States. This guide explains car insurance deductible amounts, premium effects, claim timing, waivers, and coverage exclusions.
Table of contents
- What's a Car Insurance Deductible?
- How does a Car Insurance Deductible Work?
- How Does a Deductible Affect Your Premium?
- High Deductible vs Low Deductible: Which Should You Pick?
- When Do You Pay the Deductible for Car Insurance?
- When Are You Not Required to Pay Car Insurance Deductibles?
- What Car Insurance Coverages Don't Require Deductibles?
- How Should I Choose a Car Insurance Deductible?
- Your driving record and driving frequency
- Age and condition of your car
- Leasing Company Terms
- Frequently Asked Questions
- Do I Have to Pay the Deductible if I Am Not at Fault in an Accident?
- Is My Car Insurance Deductible Applied Per Accident or Per Year?
- What's the Difference Between Collision and Comprehensive Deductibles?
- Can I change my car deductible at any time?
- Will Increasing My Deductible Always Lower My Premium?
- Do I Have Separate Deductibles for Different Types of Coverage?
- What If an Uninsured Driver Hits Me?
- Can My Financing or Leasing Company Affect My Deductible Choice?
- Can My Auto Insurance Company Waive My Deductible?
What's a Car Insurance Deductible?
A car insurance deductible is the amount of money you pay out-of-pocket to fix your vehicle before your auto insurance policy pays the rest.
Every time a covered claim is filed to your insurance provider, you have to pay your chosen deductible, and once you do, the insurer will proceed to cover the rest of the charges.
Car insurance deductibles are part of some of the more standard coverages.
Common deductibles include, but are not limited to, collision and comprehensive coverage, as well as uninsured motorist property damage and personal injury protection coverage.
Standard deductible amounts you'll typically see are $250, $500, $1,000, $1,500 or $2,000. Which deductibles are offered will depend on the insurance provider and the state you live in.
Insurers like Progressive and Geico offer smaller deductibles in some states and larger ones in others.
How does a Car Insurance Deductible Work?
After you file a claim, the insurer subtracts your deductible from the covered repair cost and pays the remaining amount. You pay the deductible to the repair shop. The insurer pays the shop the rest.
For example, let's say your vehicle gets T-boned at a busy intersection, and you lose one of its passenger doors.
Typically, the at-fault driver's liability coverage would take care of everything, but in this case, they don't have insurance. After all is said and done, the door needs to be replaced, so you submit your claim.
You receive a quote for a new car door, and the entire cost is $2,000. Now, let's say you picked the $500 deductible option from your current collision coverage.
Based on this information, your out-of-pocket costs are only $500. After paying your car insurance deductible, your insurance policy will pay the remaining $1,500, and you get your new car door.
Each auto insurance coverage you have will charge you their respective insurance deductibles separately if they go into effect.
So, if the accident you suffered turned out to be even worse and you ended up sustaining bodily injuries, you now have to pay another deductible for your personal injury protection (PIP).
Medical payments coverage pays your medical bills with no deductible. Medical payments coverage is separate from the collision deductible you owe for the vehicle damage.
High Deductible vs Low Deductible: Which Should You Pick?
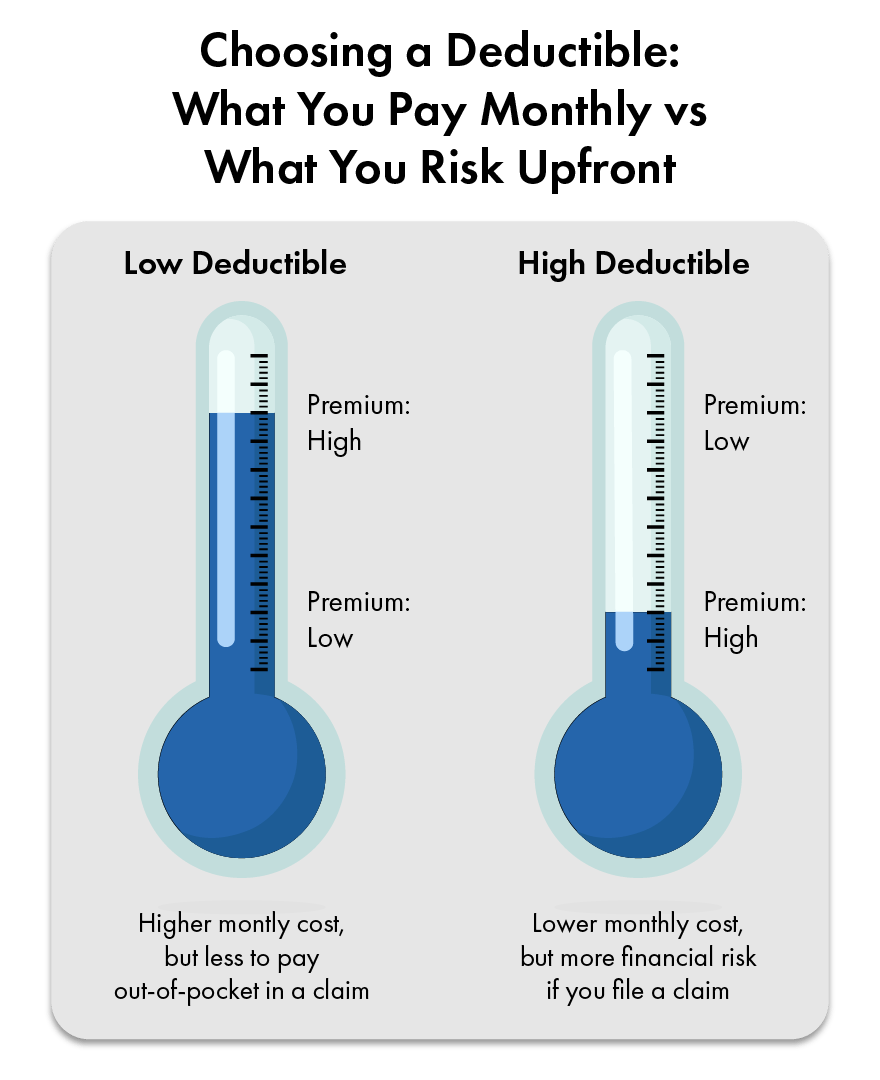
A high deductible lowers your premium and raises the amount you pay on each claim. A low deductible raises your premium and lowers the amount you pay on each claim. The premium gap between a $500 deductible and a $1,000 deductible varies by insurer. Your vehicle value, your claims history, and your savings decide which side of that trade suits you.
$500 and $1,000 are the most common choices for car insurance deductibles.
Windshield coverage has its own rules for your auto policy.
A few states remove the comprehensive deductible for glass claims. Florida law says the comprehensive deductible does not apply to windshield damage. Kentucky (since April 2024) and South Carolina pay glass-only claims with no deductible. Arizona requires insurers to offer a no-deductible glass option. Massachusetts requires insurers to offer a $100 glass deductible option. In Arizona and Massachusetts, you must select the option. Everywhere else, windshield repair comes out of your comprehensive deductible.
The windshield company Safelite processes zero dollar deductible windshield claims for Allstate, Nationwide, and USAA in the no-deductible states.
When Do You Pay the Deductible for Car Insurance?
You pay a car insurance deductible every time you file a collision or comprehensive claim for damage to your own vehicle, regardless of who caused the damage.
Personal injury protection (PIP) coverage and uninsured/underinsured motorist property damage coverage can also carry a deductible.
If your claim is filed under liability insurance coverage, which pays for property damage or injuries you cause to others, you don't pay a deductible as long as the costs are within your coverage limits.
When Are You Not Required to Pay Car Insurance Deductibles?
You won't have to pay a deductible when the driver at fault in an accident is covered by their liability policy through the insurance company paying for the damages.
This is a process known as subrogation. Some insurers may also choose to waive deductibles if you've got a specific endorsement added to your policy.
Deductible waiver endorsements differ from one insurance provider to another.
Some insurers offer diminishing deductible programs. A diminishing deductible program reduces your deductible for each year you drive without a claim.
Allstate's Your Choice Auto reduces your deductible by $100 a year for up to $500 after 2 claim free years. American Family's Platinum Choice decreases your comprehensive and collision deductible by $50 every 6 months and reaches a zero dollar deductible after 5 years. Safeco's Accident Forgiveness with Disappearing Deductible cuts $100 off your deductible a year for a maximum of 5 years. Progressive's Deductible Savings Bank cuts your collision deductible by $50 a year (up to a total of $500) for each year you do not file a claim. Nationwide's Vanishing Deductible reduces your comprehensive and collision deductibles by $100 a year up to a total of $500 if you are claim free for several years.
Full glass coverage removes any need for a deductible on your windshield except in states that don't charge a deductible at all.
In Texas, California, and Illinois, a new windshield will cost you between $250 and $400, Geico charges an extra $10-$15 per month to have your windshield replaced with a full glass coverage add on. State Farm bundles full glass coverage into comprehensive policies in Nevada and Ohio for free.
Zero dollar deductible policies are available for comprehensive and collision coverage in some states. Zero dollar deductible policies cost substantially more per year than a standard $500 deductible policy.
Personal injury protection (PIP) deductibles are set by state law and vary widely. Check your state's rules before you assume a PIP claim has no deductible.
What Car Insurance Coverages Don't Require Deductibles?
Liability coverage never carries a deductible. Uninsured motorist bodily injury coverage has no deductible. Uninsured motorist property damage coverage is the exception: in some states, uninsured motorist property damage coverage carries a deductible the same way collision coverage does. Texas requires a deductible on uninsured/underinsured motorist claims.
How Should I Choose a Car Insurance Deductible?
The right car insurance deductible is the highest amount you could pay from savings tomorrow without hardship. 3 inputs set that number: what your vehicle is worth, how often you have filed claims, and how much cash you keep on hand.
A higher deductible saves money only when you can pay the deductible. A $1,000 deductible that you would put on a credit card costs more than a $500 deductible you can pay from savings.
A common rule of thumb is a deductible of a few percent of the car's value.
Drivers who file claims every 3-5 years get a better value with lower deductibles ($250-$500). Drivers who only file claims every 10+ years save more with higher deductibles of $1000-$2000.
Having some emergency savings on hand really matters if you have a higher deductible. Financial planners say you should try to keep 3-6 times your deductible amount set aside in a savings account.
If you've got $3000 in emergency savings, a $500-$1000 deductible is probably a good bet for you. Consider all these factors listed below.
Your driving record and driving frequency
Driving record and driving frequency can also play a role in choosing a deductible.
Drivers with clean records (no accidents or traffic tickets for 3+ years) can qualify for a safe driver discount of 20-30% with insurers like Nationwide, Travelers, and American Family Insurance. That can make higher deductibles ($1000-$2000) more attractive.
Low-mileage drivers who drive under 7,500 miles on their vehicle each year can get usage based discounts of 25%-30% per year through programs like Progressive Snapshot, Allstate Drivewise, and State Farm Drive Safe & Save.
According to the IIHS, drivers who commute less than 10 miles a day are 40% less likely to get into a collision than drivers who commute 20+ miles. Higher deductibles are a good choice for people who work from home.
Age and condition of your car
Vehicles over 10 years old with a value under $5,000 usually work out financially with a higher deductible ($1000-$2000) or dropping collision and comprehensive coverage.
For example, a 2014 Honda Civic that's worth $4500 will cost you around $800 a year with a $500 deductible for full coverage. If you increase that deductible up to $1500 your annual premiums are reduced by $550 a year.
If repair costs exceed 70-80% of your vehicle's value insurers like Farmers, Hartford, and CNA are likely to declare it a total loss.
Leasing Company Terms
If you're leasing your car, the leasing company might ask you to get full coverage and specific deductible amounts.
The same applies to any other company providing you with auto loans or financing options. This is usually the only time you won't have the freedom to select the right car deductible for you.
Frequently Asked Questions
Do I Have to Pay the Deductible if I Am Not at Fault in an Accident?

Is My Car Insurance Deductible Applied Per Accident or Per Year?
What's the Difference Between Collision and Comprehensive Deductibles?
Collision Insurance Deductible: A collision deductible is for damages from a collision with another vehicle or an object (guardrail, tree, etc.)
Comprehensive Insurance Deductible: A comprehensive deductible is for non-collision events (theft, vandalism, fire, natural disasters)