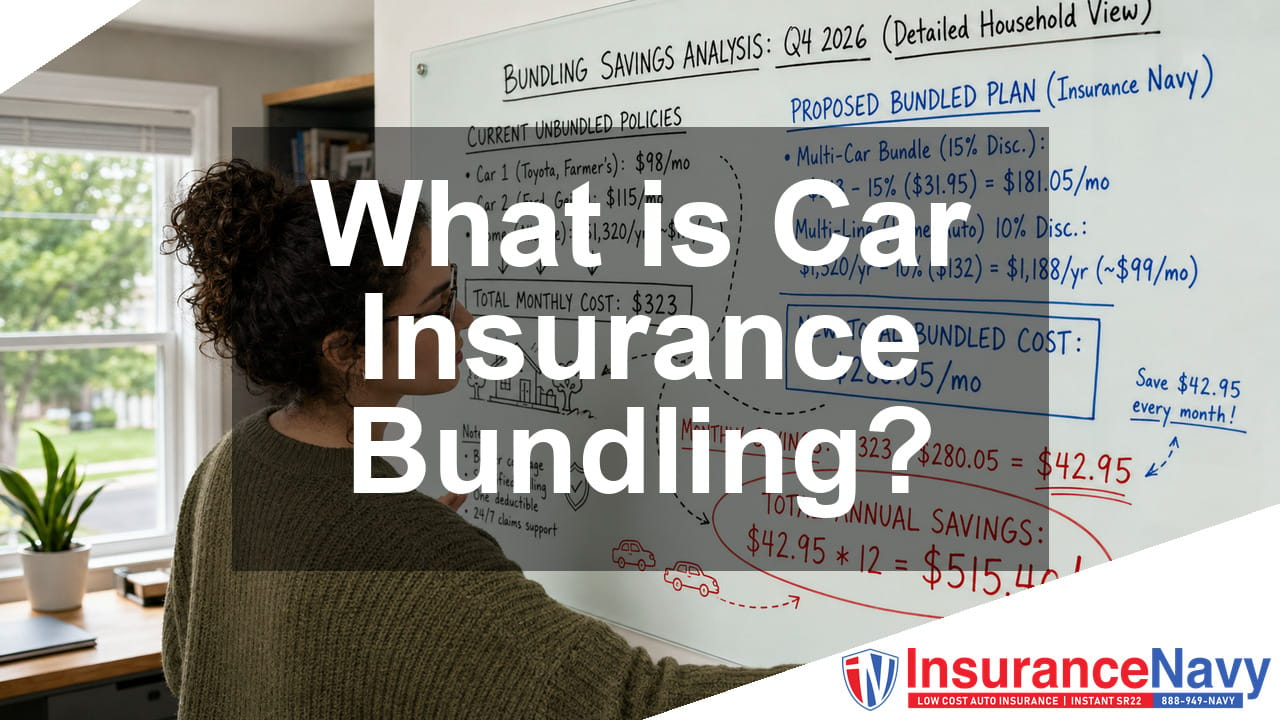
An auto and renters insurance bundle is a multi-policy package that places auto and renters coverage with one insurer. The insurer applies a multi-policy discount to the auto policy and the renters policy. An auto and renters insurance bundle carries two risks: small dollar savings and linked policies that limit switching. According to Insurance.com, the average renters insurance premium in the U.S. equals $244 a year in 2026. A 5% discount on a $244 renters premium saves about $12 a year. Renters who drive need bundled and standalone quotes to compare total annual cost. Insurance Navy helps renters compare auto and renters quotes from multiple carriers. This guide explains auto and renters insurance bundle savings, policy structure, multi-policy discounts, bundle types, and disadvantages.
Table of contents
- What Does Insurance Bundling Mean?
- How Much Can You Save by Bundling Car and Renters Insurance?
- How Does a Car and Renters Insurance Bundle Work?
- What the Bundle Includes
- How to Start a Bundled Quote
- Can You Add Renters Insurance to an Existing Auto Policy?
- What Happens If You Cancel the Renters or the Auto Policy?
- Does the Discount Move With You to a New Apartment?
- Is a Bundle Discount the Same as a Multi-Policy Discount?
- What Types of Insurance Bundles Are Available?
- What are the Benefits of Bundling Insurance Policies?
- What are the Disadvantages of Bundling Insurance?
- Should You Bundle Auto and Home Insurance?
- Bundling with Insurance Navy
- Frequently Asked Questions
- How are multi-car insurance policies bundled?
- What are the benefits of bundling renters insurance with a car policy?
- How does bundling work with an umbrella liability policy on top of auto and home?
- How do I get a better discount when bundling?
A car and renters insurance bundle is a pair of policies, auto and renters, bought from the same insurer in exchange for a multi-policy discount on both. The discount on this pairing is small: 1% to 6%, or about $114 a year on average, per Insurance.com's May 2026 rate analysis.
Home and auto bundles save more, about 15% or $869 a year. Judge the 2 pairings by dollar savings, not by the same headline percentage.
Is it the right move for you to bundle insurance? Keep reading to explore the pros, cons, and smart strategies behind auto insurance bundling.
What Does Insurance Bundling Mean?
Insurance bundling is buying multiple types of coverage, home, auto, renters, life, or even boat and RV insurance, from a single company.
Insurers offer bundling to retain customers. Policyholders get a discount on each bundled policy.
Many insurers assign a dedicated agent to review the bundled policies each year.
The main benefit of bundling is the multi-policy discount on each policy. The size of the discount depends on the pairing.
Despite recently rising base premiums, bundling discounts have stayed the same. It's a smart way to manage increasing insurance costs.
There is a trade-off: your policies are linked.
Suppose you want to switch carriers for better service or pricing. In that case, you'll have to move all policy bundles together, which can limit flexibility.
How Much Can You Save by Bundling Car and Renters Insurance?
Bundling car and renters insurance saves 1% to 6% a year, or $9 to $182. The average saving is about $114. The figures come from Insurance.com's May 2026 analysis of Quadrant Information Services rate data across all 50 states and Washington, D.C. The discount is smaller than a home and auto discount because a renters premium is small, so the percentage applies to a small premium.
Insurer | Average annual saving | Discount |
|---|---|---|
Farmers | $182 | 6% |
Progressive | $146 | 6% |
State Farm | $138 | 5% |
Allstate | $132 | 4% |
Nationwide | $132 | 5% |
Travelers | $103 | 5% |
GEICO | $73 | 3% |
USAA | $9 | 1% |
Source: Insurance.com rates for a 40-year-old driver with good credit and a clean record, $500 auto deductibles, and $40,000 of renters personal property coverage.
Carrier marketing figures run higher because carriers measure a different thing. Allstate advertises up to 5% off the 2 policies combined, about $75 a year on a $1,200 auto premium plus a $300 renters premium. Progressive reports $795 in average savings for customers who switched both policies to Progressive between June 2024 and May 2025. The Progressive figure counts the whole switch, not the bundle discount alone.
The bundle is worth it when the bundled total beats the standalone total. The bundled total is the price of both policies from 1 insurer with the discount applied. The standalone total is the cheapest auto quote plus the cheapest renters quote from any insurers. The lower total wins, not the larger discount.
How Does a Car and Renters Insurance Bundle Work?
A bundle is still 2 separate policies with 2 policy numbers, 2 renewal dates, and 2 sets of limits. The insurer links the 2 policies to 1 account and applies the multi-policy discount to each policy.
What the Bundle Includes
The auto policy carries your liability, collision, and comprehensive coverage as usual. The renters policy covers your personal property, your liability inside the rental, and additional living expenses if the unit becomes unlivable. Many landlords require at least $100,000 of renters liability coverage. Most insurers raise the limit to $300,000 for a few extra dollars a month. Renters deductibles usually run $250 to $1,000.
How to Start a Bundled Quote
Get a standalone quote for each policy from at least 1 other insurer, so you know the price the discount has to beat.
Quote the auto policy and the renters policy together with the insurer you are considering. Ask for the multi-policy discount on both policies and for the total annual cost of the pair.
Choose the lower total, not the larger discount.
Can You Add Renters Insurance to an Existing Auto Policy?
Yes. Buying the renters policy from your auto insurer adds the multi-policy discount to the existing auto policy. Progressive, for example, states that quoting and buying renters insurance with Progressive applies the discount to your Progressive auto policy. You do not need to wait for the auto policy to renew.
What Happens If You Cancel the Renters or the Auto Policy?
The remaining policy loses the multi-policy discount. The insurer reprices the remaining policy as a single policy, usually at the next renewal.
Does the Discount Move With You to a New Apartment?
Yes, as long as the renters policy stays with the same insurer. Update the renters address and the auto address at the same time, because the garaging address changes the auto rate.
Is a Bundle Discount the Same as a Multi-Policy Discount?
Yes. Bundle discount, multi-policy discount, and multi-line discount are 3 names for the same price break. The price break is a percentage off each policy when you hold 2 or more policies with 1 insurer. A multi-car discount is a different discount. A multi-car discount applies to a second vehicle on the same auto policy. The 2 discounts can stack.
What Types of Insurance Bundles Are Available?
Insurance bundles are individual coverage types bought from 1 insurer, each under its own policy. They simplify policy management, increase coverage, and often reduce overall premium costs.
Insurers allow most policies to be customized. Some combinations are more popular because customers frequently need all types of insurance policies anyway.
Some Common Insurance Bundle Combinations are listed below.
Home Insurance and Auto Policies: The most common insurance bundle for homeowners who own cars.
Renters Insurance and Auto Policies: For renters with personal vehicles. This makes keeping track of insurance policies easy and covers the home and vehicle.
Condo Insurance and Auto Policies: For condo owners. The condo (HO-6) policy covers the unit interior and the owner's belongings.
While the above are the most popular, your insurer probably offers more bundling options. Insurers often allow customized policies for customers' financial protection needs.
Other types of policies that can be bundled but less frequently are listed below.
Vacation Home Policy: For second homes or seasonal properties.
RV Policy: This is for recreation vehicle owners who use their RVs for travel or leisure.
Boat Policy: For watercraft protection against damage, theft, and liability.
ATV Policy: For off-road vehicle owners using ATVs for recreation or utility.
Motorcycle Policy: For two wheel vehicles. Policies can cover bodily injury, property damage, and collision.
Life Policy: Part of a broader financial protection plan for families.
Flood Policy: Supplements homeowners insurance, especially in flood areas.
Umbrella Policy: Extends liability coverage across existing policies and adds extra protection frequently up to 1 million dollars.
Pet Policy: Assists with vet bills for dogs and cats.
Business Policy: For business owners, it combines property, liability, and employee coverage.
What are the Benefits of Bundling Insurance Policies?
The benefits of bundling fall into 4 areas: operational ease, claims efficiency, financial benefits, and consistent service.
Operational Ease: When you have all your policies under one provider, you can manage all your coverages in one place. Policyholders can access and see all their policy features in one online portal. This reduces the hassle of dealing with multiple insurance carriers. Billing is also combined into one bill. This makes it easier to track and less likely to miss a payment.
Claims Efficiency: Bundling policies makes the claims process easier by allowing policyholders to deal with one company for multiple claims. This helps in events that affect more than one insurance policy, like a natural disaster that damages both a home and a vehicle. A single claims adjuster can handle related claims at the same time and resolve them faster for the customer.
Financial Benefits: Bundling may also qualify policyholders for a single deductible across multiple policies. Suppose a covered event affects more than one insured item. You might only pay one deductible for each policy instead of separate ones. Bundling may also give you access to higher liability limits, additional policies like roadside assistance, or optional add ons at discounted rates.
Service Consistency and Personalized Support: Having all your policies with one insurance carrier means quality customer service and comprehensive coverage. The insurance company can get to know the policyholders needs better. They can make personalized recommendations about their policies. This relationship allows for better-informed changes to your insurance policy terms.
What are the Disadvantages of Bundling Insurance?
Bundling has 4 drawbacks: limited specialized coverage, worse rates for high-risk drivers, limited product offerings, and savings too small to matter, especially on a car and renters pair.
A few scenarios where having your policies with separate companies is warranted are listed below.
Specialized Coverage Needs: Some homes and vehicles require specialized coverage that bundled policies don't offer. For example, high-value homes or properties in high-risk areas, flood zones or wildfire-prone areas, may need a specialized homeowners policy that isn't available from auto-only insurers. Luxury, collector, and antique cars often need specialized policies that aren't compatible with bundled options.
Drivers who are High Risk: High-risk drivers with multiple accidents or DUIs may find lower rates with high-risk auto insurance companies. These non-standard insurers offer lower rates than standard companies even with a bundled discount. Drivers with a clean driving record, even those with teenage drivers, may get better rates or more features like accident forgiveness by separating their auto and home policies.
Limited Product Offerings: Not all insurers offer the full range of insurance products needed for a comprehensive bundle. For example, an insurer may provide auto insurance but not life or umbrella insurance. This limits your ability to bundle coverage and may require you to buy a policy from another insurance company.
Not Enough Savings: Bundling doesn't always guarantee more savings. In some cases, the savings are small and not worth consolidating policies. When comparison shopping, you may find that bundled quotes from one provider may still be more expensive than separate quotes from different insurers. Insurance premiums vary widely based on underwriting models, and comparing standalone policies from multiple providers may find you more competitive insurance rates or better coverage.
Bundling isn't always the best option. You should assess your individual risk profile, coverage needs, and pricing scenarios to determine whether keeping separate policies is better for you.
Should You Bundle Auto and Home Insurance?
Yes, for most households. Home and auto is the pairing with the largest bundle discount, and both premiums are large enough for the discount to matter.
Insurance companies view bundled policyholders as lower risk.
Insurers price lower risk with lower rates or more coverage.
So, while bundling is good, compare bundled and standalone quotes to see what's best for you.